In recent years, Puerto Rico has become one of the most prominent locations for U.S. citizens to relocate to. A major attraction has been the generous 100% local tax exemptions for Puerto Rico-source interest and dividends, as well as capital gains, introduced originally under Act 20 and Act 22 and now consolidated under Puerto Rico Act 60 (The Tax Code of Puerto Rico).
Under 26 U.S.C. § 933, income derived from sources within Puerto Rico by an individual who is a bona fide resident of Puerto Rico for the entire tax year is generally excluded from U.S. federal gross income and exempt from U.S. federal income tax. Capital gains accrued after attaining bona fide Puerto Rico residency benefit from a 100% tax exemption from both U.S. and Puerto Rico taxation.
Pre-Move vs. Post-Move Capital Gains Rules
Even if capital gains accrued prior to establishing Puerto Rico residency remain subject to U.S. tax for 10 years after moving, significant tax savings can be realized on all additional appreciation accruing after establishing Puerto Rico residency. However, as reaffirmed in IRS Chief Counsel Memorandum 2024-05, pre-residency gain (whether held directly or through pass-through entities like S corporations and partnerships) remains fully subject to U.S. federal income tax when realized.
Puerto Rico is one of fourteen U.S. territories or possessions, only five of which are permanently inhabited (Puerto Rico, Guam, U.S. Virgin Islands, American Samoa, and Northern Mariana Islands). The Internal Revenue Code applies distinct tax rules for residents of Puerto Rico compared to residents of the 50 U.S. states.
Internal Revenue Code Section 933 does not exempt residents of Puerto Rico from paying U.S. federal taxes on U.S.-source income or foreign-source income. In general, dividends are sourced to the location of the paying corporation under 26 U.S.C. § 861(a)(2), while interest amounts are sourced to the residence or country of incorporation of the obligor under 26 U.S.C. § 861(a)(1).
The Three-Part Statutory Test for Bona Fide Puerto Rico Residency
Under 26 U.S.C. § 937 and Treasury Regulation § 1.937-1, an individual is treated as a bona fide resident of Puerto Rico during a taxable year if three distinct statutory tests are satisfied:
1. Presence Test
Must spend at least 183 days in Puerto Rico during the tax year, OR satisfy one of four alternative presence tests under Treasury Regulation § 1.937-1.
2. Tax Home Test
Must not have a tax home outside Puerto Rico during any part of the tax year. Your tax home is your principal place of business or regular post of duty.
3. Closer Connection Test
Must not maintain a closer connection to the United States or a foreign country than to Puerto Rico, based on all facts and personal ties.
Understanding the 5 Alternative Presence Tests
To satisfy the physical presence requirement under IRC § 937(a), you must meet at least ONE of the following five alternative tests during the tax year:
| Presence Test | Statutory Requirement | Key Condition |
|---|---|---|
| 1. 183-Day Rule (Primary) | Present in Puerto Rico for at least 183 days during the tax year. | Standard test used by most Act 60 decree holders. |
| 2. 549-Day 3-Year Rule | Present in Puerto Rico for at least 549 days over a 3-year period (current tax year and 2 preceding tax years). | Must spend at least 60 days in Puerto Rico during each year of the 3-year period. |
| 3. 90-Day U.S. Limit Rule | Present in the United States for no more than 90 days during the tax year. | Useful for frequent international travelers. |
| 4. $3,000 Earned Income Test | Had $3,000 or less of earned income from U.S. sources during the tax year. | Must also spend more days in Puerto Rico than in the U.S. during the tax year. |
| 5. No Significant U.S. Connection | Had no significant connection to the United States during the tax year. | Must have no U.S. permanent home, no U.S. voter registration, and no spouse or minor child residing in the U.S. |
Under the No Significant U.S. Connection Test, a taxpayer is deemed to have a significant connection to the U.S. if: (1) they maintain a permanent home in the U.S. (including a furnished room or leased apartment held available for long durations); (2) they hold an active voter registration in any U.S. political subdivision; or (3) they have a spouse or minor child under age 18 whose principal place of residence is in the U.S. (unless living under a custody decree or attending school as a full-time student). See Treas. Reg. § 1.937-1(c)(5).
How Days Are Counted for Puerto Rico Presence
Under 26 U.S.C. § 7701(b)(7)(A) and Treasury Regulation § 1.937-1, presence in Puerto Rico at any time during a calendar day counts as a full day of presence in Puerto Rico.
If you are physically present in both the United States and Puerto Rico during the same calendar day (e.g., a flight travel day), that day is counted as a day of presence in Puerto Rico. In addition, days spent outside Puerto Rico for qualifying medical treatment for yourself or immediate family members, or due to mandatory government evacuations or major disaster declarations, can also count as days in Puerto Rico under specific conditions in Treasury Regulation § 1.937-1.
The Tax Home and Closer Connection Requirements
The Tax Home Test: You cannot maintain a tax home outside Puerto Rico during any part of the tax year. Under IRC § 911(d)(3), your tax home is your regular or principal place of business, employment, or post of duty. If you do not have a regular place of business due to the nature of your trade or retirement, your tax home is where you regularly reside.
The Closer Connection Test: You must maintain more significant personal, economic, and social ties to Puerto Rico than to the U.S. or any foreign country. When evaluating your closer connection, tax authorities and courts inspect:
- Location of your primary, permanent family home;
- Location of your spouse, children, and immediate family;
- Location of active social, political, cultural, professional, or religious affiliations;
- Location where routine personal and business banking is conducted;
- Jurisdiction issuing your primary driver's license and vehicle registrations;
- Charitable organizations to which you actively contribute; and
- Official state of residence designated on tax filings, estate documents, and contracts.
IRS Form 8898 Filing Requirements
Under Section 937(c) of the Internal Revenue Code, individuals who establish or cease bona fide residency in Puerto Rico or another U.S. territory must file IRS Form 8898 (Statement for Individuals Begins or Ends Bona Fide Residence in a U.S. Possession).
Form 8898 must be filed for any tax year in which you meet both of the following conditions:
- Your worldwide gross income for the tax year is more than $75,000; AND
- You take a position for U.S. tax purposes that you became or ceased to be a bona fide resident of Puerto Rico (or another U.S. territory like the U.S. Virgin Islands, Guam, or CNMI).
Automated Residency Day Count Tracking for Puerto Rico
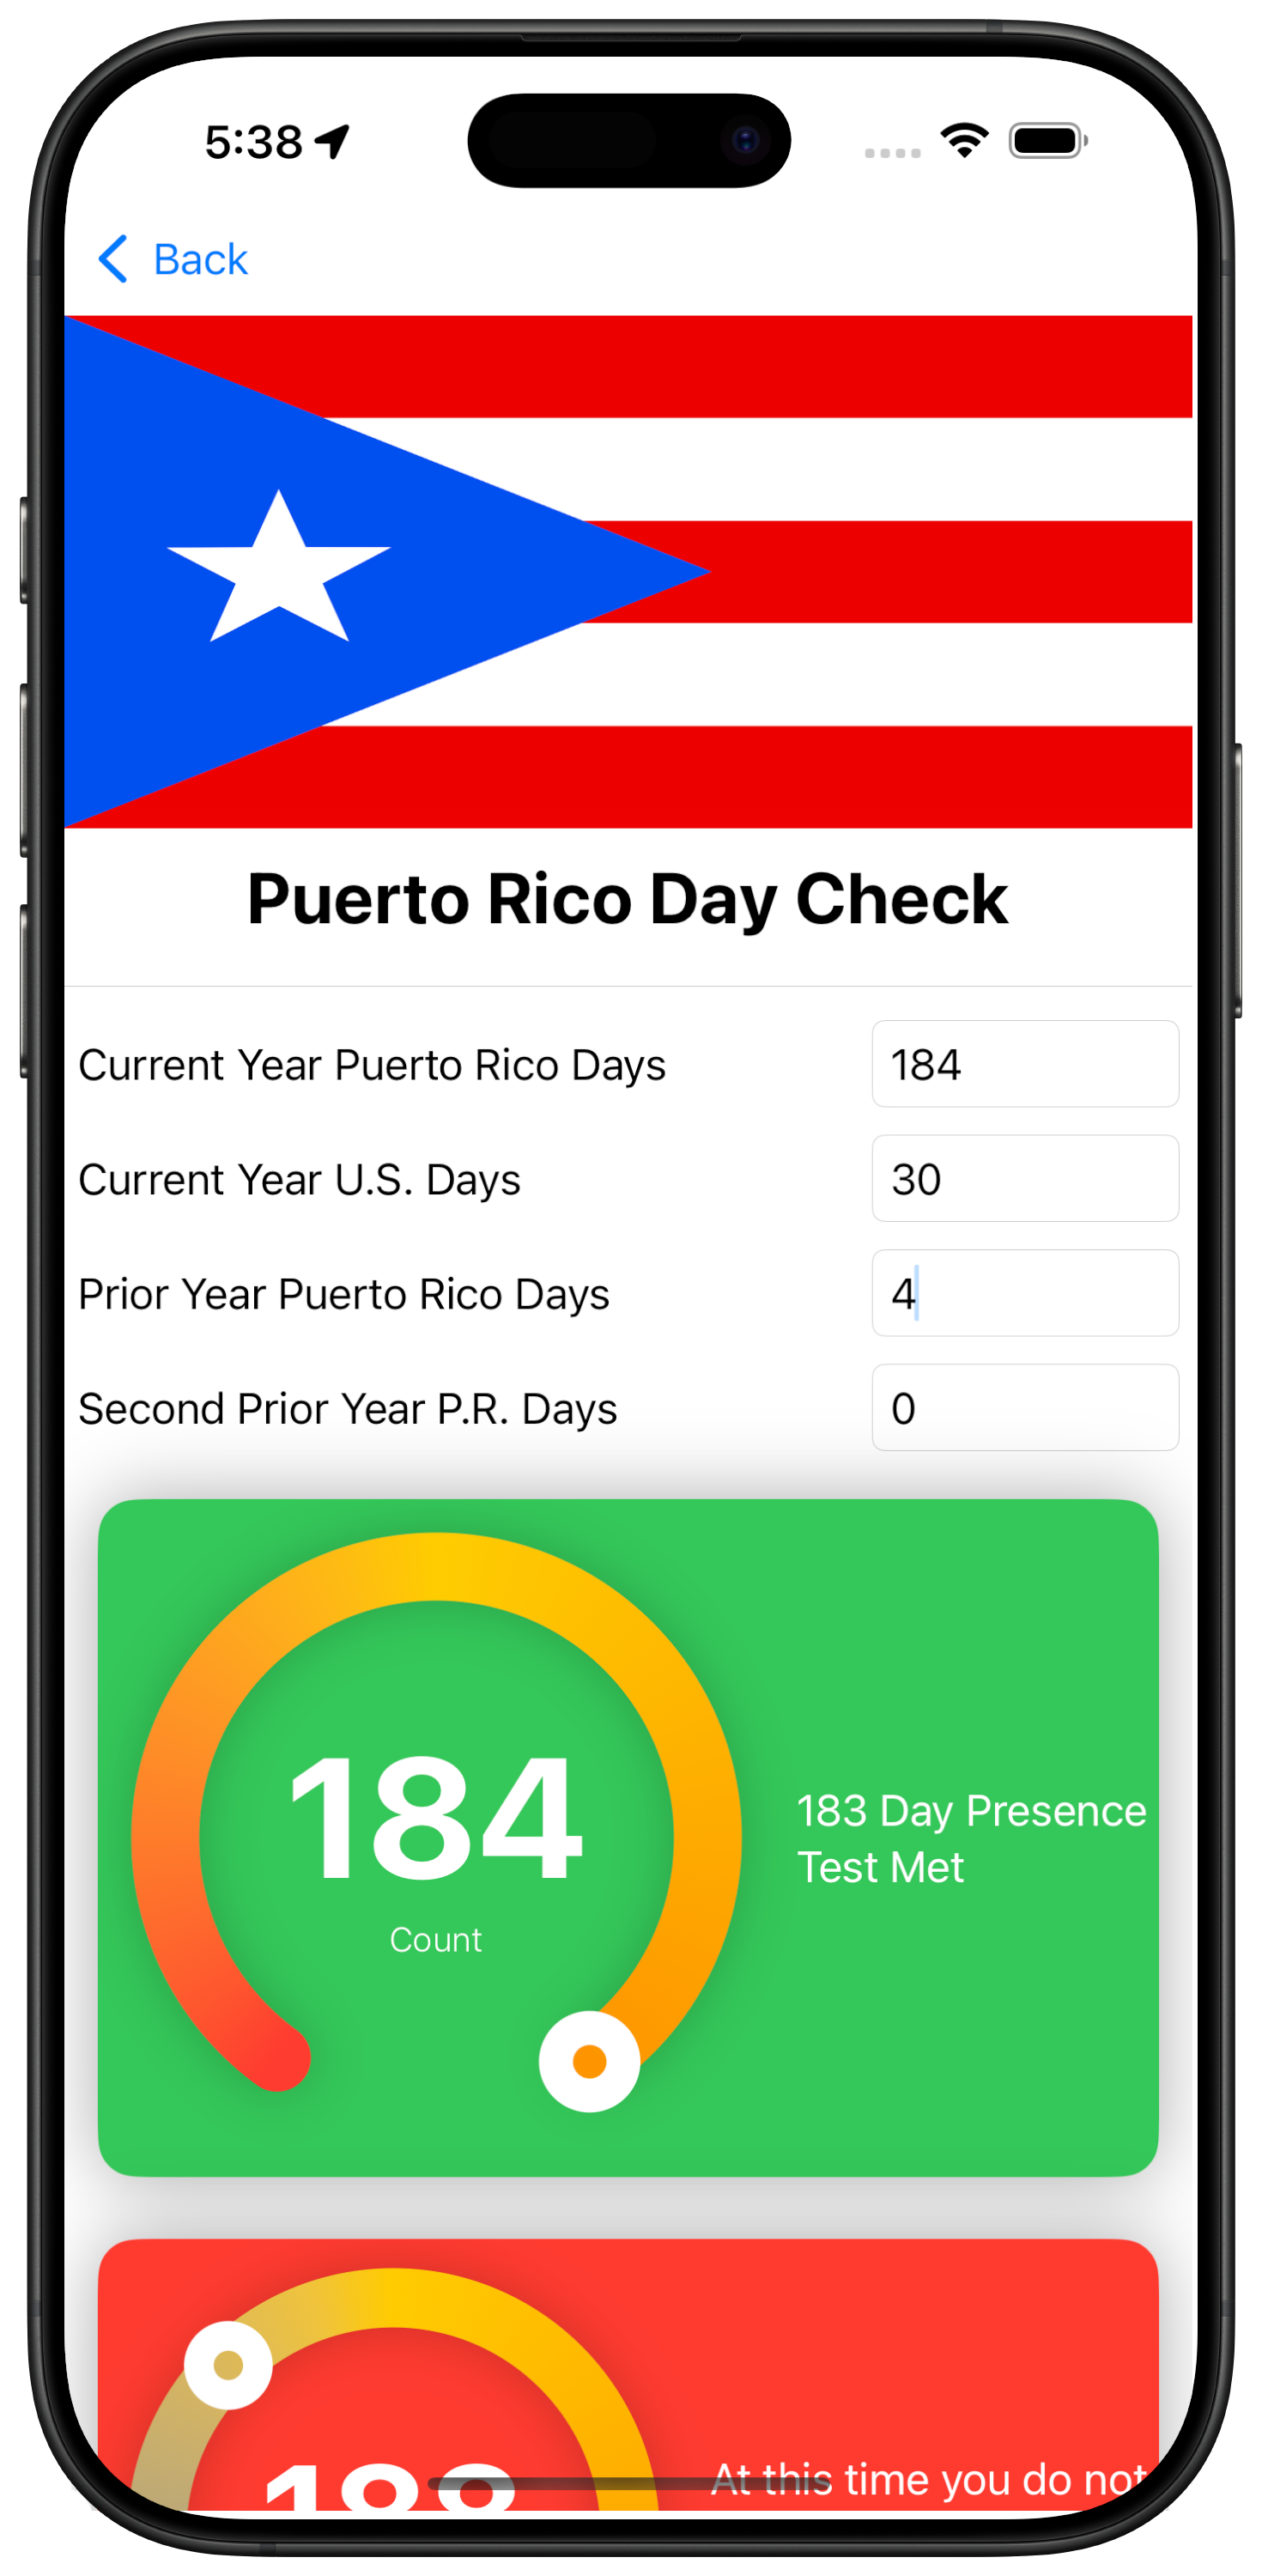
Day count tracking is an important element in documenting bona fide Puerto Rico residency under IRC § 937. The Domicile365 App features dedicated Puerto Rico presence tracking tools, automated 183-day and 549-day threshold alerts, and location logs signed via Apple App Attest and Google Play Integrity to help substantiate your physical presence.
For full details on automated location logging and mobile audit trails, view our Software Overview Page or download Domicile365 on iOS, Mac, and Android.
IRS & GAO Compliance Scrutiny: Avoiding Audit Pitfalls
Establishing Puerto Rico tax residency requires strict, ongoing compliance. The U.S. Internal Revenue Service maintains an aggressive Large Business & International (LB&I) Active Campaign on Puerto Rico Residency to audit high-net-worth individuals claiming Act 60 benefits without satisfying physical presence or income sourcing rules.
Increased Enforcement, Civil Audits & Criminal Prosecution
The IRS and U.S. Department of Justice have brought federal criminal indictments against individuals and tax advisors who falsified presence records or improperly claimed exemptions. See U.S. v. BDO Partner Indictment.
In news release IR-2023-126, the IRS warned that it identified over 100 high-income individuals claiming Puerto Rico tax benefits without meeting statutory residency or sourcing rules, actively referring non-compliant cases to criminal investigation.
Congressional oversight has also intensified, as reflected in Senator Wyden's Inquiry into Act 60 Decree Holders and IRS Chief Counsel Memorandum 2024-05.
Reinforcing this enforcement focus, a comprehensive December 2025 GAO Report highlighted ongoing gaps in data sharing between Puerto Rico tax authorities and the IRS, recommending systematic data exchanges and expanded mandatory audits of Act 60 decree holders.
Disclaimer: This material has been prepared for informational purposes only, and is not intended to provide, and should not be relied on for, tax, legal, or accounting advice. You should consult your own qualified tax, legal, and accounting advisors before engaging in any transaction or relocation.
Protect Your Puerto Rico Tax Residency Status
Don't leave your bona fide residency compliance to chance. Use the Domicile365 App to maintain detailed, contemporaneous location logs to help document your physical presence for Section 937 compliance.
Sign up for a free 60-day trial and start tracking today.
Trusted Coverage & Media
As seen in Kiplinger, Fortune and the Pennsylvania CPA Journal.